
Novellas with groff
The Kluever Maneuver
Is it okay to share my experiments implementing research papers on my own LLM here? [P]
Hey everyone!
I've built and trained a small LLM (~8M parameters) from scratch using PyTorch, mainly as an experimental lab where I can implement and test ideas from different research papers.
I've been documenting the whole journey through casual blogs, including my mistakes, experiments, and things I've learned.
So far:
Next up is KV caching, followed by PagedAttention, Orca, and whatever else I find interesting.
Just wanted to ask if sharing these experiments and blogs here would be welcome. Nothing promotional, just me experimenting, learning, and hopefully getting feedback from people who know more than I do.
[link] [comments]
Is neuro-evolution relevant? [D]
I've experimented using neuro-evolution to train AI to play a variety of different games and I'm just curious as to how or if this technique is actually really used anywhere in industry or if people are doing research on this. I'd assume it'd probably relate with reinforcement learning in some way but I'm not entirely sure about that
[link] [comments]

I built a scikit-learn for RSI [P]
 | After reading a bunch of RSI papers, I keep coming back to familiar problems from RL and evolutionary search:
That motivated us to build Gear, an open-source, meta-learning-inspired framework. A task agent produces execution traces; a meta-agent uses those traces and evaluation feedback to improve prompts, tools, workflows, and context management. Gear separates search decisions from execution and evaluation. Our goal is a scikit-learn for RSI, making approaches such as GEPA, RRSI, and Harness² easier to implement and compare. We currently have a working GEPA variant with shared failure diagnosis and staged evaluation. With GPT 5.6 Luna held at medium reasoning effort, we observed these task pass rates:
At max effort on Marketing, Luna with the optimized harness reached 88.88% objective completion, versus 84.08% for Astra + Codex. Strict task pass rates were 53% versus 57%, so the advantage was in partial completion. Separately, with both models using the same optimized DSH at max effort, Luna’s estimated API cost averaged $0.0568 per task versus $1.1858 for Astra—95.21% lower, excluding optimization and infrastructure costs. We’d welcome feedback on candidate evaluation and diversity preservation under limited budgets. [link] [comments] | |||||||||||||||

Hierarchical detection of neonatal brain pathologies using a two-stage deep learning framework from magnetic resonance imaging [R]
 | submitted by /u/rottoneuro [link] [comments] |
Are there fundamental repeating patterns in ML techniques across modalities (text, image, audio) that let us group them? [R]
I’ve been noticing that a lot of techniques seem to repeat across modalities with just a different name.
For example, tokenisation, masking (MLM / MAE / audio masking), diffusion, next-token / next-frame prediction, etc.
Is there an existing taxonomy or mental model that groups ML techniques by their underlying pattern rather than by modality (NLP / vision / audio)?
This will help me to group the research papers and then make reference to work already done in that domain
[link] [comments]
Surviving "The Graduate"
EqualAI CEO: Your AI assistant is acting in your name. Who signed off?
This summer, investor Katie Jacobs Stanton said her AI assistant, Instinct, sent an email on her behalf without consulting her first, according to TechCrunch. She described the email as innocuous. The breach of trust was not.
Next time, it could be the email that costs someone a job, a marriage or a lawsuit.
The appeal of personal AI agents is compelling. An assistant that can identify priority emails and draft responses, remember your mother-in-law’s birthday and buy a present based on your correspondence is enticing. For people stretched by demanding jobs, caregiving, or a disability, that help can be transformative. But Stanton’s experience raises an important question: when we give an assistant access to our lives, how do we retain control? Assistants such as Instinct and Meta’s Muse act for us rather than simply answering questions or making recommendations. A mistaken purchase may be refundable. An intimate disclosure cannot be taken back.
The harms are already emerging. Forbes reported that when investor Jason Yeh asked Instinct to find open dinner reservations, it booked a table instead, leaving him with a $200 cancellation fee he never approved. TechCrunch reported that one tester couldn’t get his data deleted, and another received an inbox summary hours after disconnecting her account. And in September, security researcher Patrick Wardle exposed a flaw in Muse’s Mac app that could let malware already on a computer hijack the assistant, which Meta quickly patched.
The problem now reaches our bank accounts, too. Last week, major financial institutions reported that personal AI agents were operating inside online accounts. In one case, an agent called a bank without authorization to file a complaint. JPMorgan Chase CEO Jamie Dimon said the bank would not allow unvetted “outside agents to come in inside the company”, and Schwab’s CEO said they’re actively blocking unauthorized agents. White House adviser David Sacks countered that data was shared willingly and these are “in no way cyberattacks.” Each side has a point, which is precisely the difficulty. We have not yet settled on what authorization means when the party acting is software.
The failures are also hard to see. A public record launched this week by the security firm Manifold counts 59 incidents since July 2025, forty-two of them disclosed in the past four months alone. The median incident took 70 days to come to light, and only 11 of the 59 were detected by a security control.
At EqualAI, we have long maintained that good AI governance is good business because trust will ultimately determine whether people adopt these tools at all. We recently convened senior executives who develop and deploy agents to work through a simulated crisis. The exercise exposed the same gaps repeatedly. In our mock company, without sufficient AI governance, audit trails were too thin to reconstruct what an agent had done. Vendor contracts were silent on who answers when an agent errs. Responsibility for oversight was assumed rather than assigned. These gaps were most acute where speed had outrun precaution. Those gaps shaped the roadmap that came out of the exercise.
The legal landscape is moving in the same direction. California law now prevents companies from avoiding civil liability by arguing that the AI acted autonomously. Senators Hawley and Murphy proposed extending federal anti-hacking law to developers and operators whose agents recklessly cause damage.
Those same principles should apply to the assistants people are bringing into their homes. For consumers, they translate into four commitments.
Make permission specific. An assistant should receive only the access a task requires. Permission to read your inbox should not automatically become permission to send emails in your name. Before an assistant spends money, changes who can access an account or shares sensitive data, there should be safeguards in place, which are known to users.
Assign responsibility in advance. If an assistant wrongly cancels your flight, the remedy must be clear. Companies should determine in advance of deployment who investigates an assistant’s unauthorized actions, who can halt them and how users are made whole.
Test with users’ perspective. Independent testing should confirm that assistants ask before acting, respect their limits and fully disconnect when access is revoked. Because models change constantly, testing must be continuous. Wardle’s discovery was valuable. Work like his should be the norm.
Report and study failures. Aviation became one of the safest forms of travel in part because pilots and airlines report near misses and investigators learn from them. Companies should be expected to identify an “AI incident”, preserve the records, notify those affected and correct the underlying cause, while policymakers can establish reporting requirements for serious cases.
Consumers also have a role. They need to understand permissions they’ve granted and how to revoke its access. But the greater responsibility rests with companies selling the tools to define their limits and set reasonable expectations. We shouldn’t need a cybersecurity background to use these tools safely.
We board planes without understanding how they fly because industry and regulators answer for our safety. We need a similar framework for AI assistants. If companies want our inboxes, accounts and errands, they must earn our trust by clarifying what we’re authorizing, how to regain control, and answer for mistakes their assistants make in our name.
The opinions expressed in Fortune.com commentary pieces are solely the views of their authors and do not necessarily reflect the opinions and beliefs of Fortune.
This story was originally featured on Fortune.com
This top data scientist’s (non-AI) model finds Republicans have just one chance in six of holding Senate
I started following Thomas Miller’s political forecasts during the January 2021 Senate races in Georgia. Just a few days before the election, the polls and pundits anticipated a relatively easy win for both Republican candidates. But Miller—a prominent data scientist and professor at Northwestern University—posited a Democratic sweep, and he was right. He also called Trump’s victory in 2024. What’s different about Miller’s models? They’re far more current than the polls, and they’re centered on prediction market prices that are typically a better guide than the voter surveys—plus Miller adjusts the outlook in every Senatorial contest by using all we know about every contest.
Now, Miller is applying an updated version of his model for the current Senate elections. You can find the stats on his website, Virtualtout.io, and I highly recommend paying a visit. Once again, Miller starts by incorporating the betting venues’ data. “I use the numbers from two sites, Polymarket and Kalshi,” he told Fortune. “They’re the ones that trade the most dollars, where most of the action happens.” Miller then calibrates the posted “prices” so that they reflect probabilities, and the odds for both leading candidates tally to 100%. In a further step, he deploys multiple time series analysis to find underlying factors driving the betting prices, and uses trusted models from finance and economics to project how they’re likely to influence voters moving forward.
By the way, he thinks his model works better than AI.
Miller updates the probabilities of a Republican or Democratic win every 10 minutes. The odds that a candidate will win scroll across the top of the Virtualtout.io screen continuously, in a band resembling a stock ticker tape. For each race, Miller also posts the change over the last 24 hours. Miller calls the streaming feature the “NowCast.”
As for those “underlying” factors, one force swamps all others: Donald Trump. “The states don’t move independently of one another,” says Miller. “If one goes up for Democrats, chances are they’ll all go up for Democrats, and vice versa. The entire market is dominated by what Trump does and says hour by hour.” Put simply, when voters don’t like the POTUS’s words or actions, all Republican odds tend to fall. Miller asserts that his model has identified 85% to 90% of what’s causing the variances on Kalshi and Polymarket, and “my interpretation is that it’s overwhelmingly Trump and the Republican positions generally.”
Though he opened Virtuatout.io to public view about a week ago, Miller started running the numbers on September 17. What’s most striking is just how far the GOP chances have faded in just six weeks.
As of around 9 AM on October 30, five days before most polling sites close, Virtualtout.io gives the Republicans a 17.1%, or just over one-sixth probability, of winning 50 seats and hence retaining control of the upper chamber. On September 17, that figure was twice as high at 34.8%, or slightly better than one-in-three. In all five contests where the Democrats can flip a seat, their chances are better than 60%—in most cases, much better.
In North Carolina, where Republican Thom Tillis is retiring, leaving an open seat, the GOP was never remotely close, and now harbors a minuscule 4% shot at victory. In Texas, the Republican odds have dropped since September 17 from 46.15% to 31.9%, in Ohio from 45.4% to 31.8%, and in Alaska from 32.95% to 28.6%.
In only one state is the GOP faring better than in mid-September and that’s Maine. Republican Susan Collins started as an underdog at 32.6%, but has clawed back to 39.9%, adding 1.7 points in the last 24 hours. In Alaska, things are also looking up for the Republicans: After falling to a low of 23.4% on October 23, incumbent Dan S. Sullivan’s prospects have improved by over 5 points to 28.6%.
For the political pros looking for harbingers of big trouble for either side, the towering sign is the Republican woes in traditional strongholds Iowa and Kansas. In the former, Republican Ashley Hinton dropped from 61.75% on September 17 to a virtual tie at 53.4%, a trend mirrored in Kansas where Roger Marshall was looking a likely victor six weeks ago at 75.8%; now, he’s down almost 19 points at 57.1%. In the last day, Hinton and Marshall have shed 1.45% and 2.47 points respectively.
In the one state where Republicans saw a big chance for a flip, the horizon’s receding fast. The GOP chances of beating Abdul El-Sayed in Michigan have slipped from better than a third in mid-September to about a quarter (25.4%).
If the Democrats indeed score a flip in every contest where their probabilities in Miller’s model stand at 60% or better, and hold all the seats they have now, they’ll clinch a majority of 52 to 48, nearly reversing the Republican dominance at 53-47.
In South Carolina, recently rerated on the Fox News Channel from “lean Republican” to “tossup,” Miller still has Darline Graham at a commanding 75%, though she’s slipped 2.4 points in the past 24 hours.
Keep in mind that Miller’s setting odds, not making definitive predictions. A candidate at over 30% still stands a decent chance of winning. And Republicans are over that bogey in Maine, Ohio, and Texas, and close and trending the right way in Alaska. Odds-defying events happen all the time. The problem for Republicans is that they’d have to beat those odds multiple times, plus defend seats they never dreamed they’d have to defend.
It’s still far from over. And one of the best places to get a plausible, non-AI driven snapshot from a data scientist who’s been doing this for six years, is that NowCast on Tom Miller’s Virtualtout.io.
This story was originally featured on Fortune.com
U.S workers just took home their smallest share of capital since at least 1947—and the lowest ever recorded
As corporate earnings soar and U.S. GDP balloons, the American workforce isn’t feeling the same boom. American workers are taking home less of the country’s overall income, data from the Bureau of Labor Statistics shows, and employment in the U.S. is set to continue to slow.
Labor share, or the portion of the U.S.’s economic output that workers receive through salary and wages, decreased to 52.8% in the second quarter of 2026, its lowest level since the BLS started recording this data in 1947, according to its labor productivity and costs report. In the previous quarter, labor share was at 53.6%. This decade, the labor share average was about 55.6%.
That’s despite corporate earnings skyrocketing, with profits for Fortune 500 companies hitting a record $2.1 trillion in 2025. The U.S. GDP grew 3.4% in the third quarter last year, exceeding economists’ predictions.
That growth has not only come at the expense of how much of the pie of wealth workers are taking home, but also how many Americans are in the workforce, economists warn.
“That decline in the share of labor has got to be either falling earnings or falling numbers of people,” Raymond Robertson, a labor economist at Texas A&M’s Bush School of Government, told Fortune. “The falling share of income is having to do with the shift towards capital.”
Indeed, there are growing signs that as national income balloons, the U.S. workforce is deflating. Unemployment ticked up to 4.2% in September, and employers added just 584,000 jobs in 2025 compared to 2 million added in 2024. The U.S. added 29,000 jobs in September, about one-third of economists’ projections.
The bifurcation of corporate victories and weak labor data raises concerns among economists of jobless growth jeopardizing the U.S. workforce, as well as a K-shaped economy, where the rich get richer while the poor get poorer, becoming more exaggerated.
“Data right now is very mixed,” Robertson said. “But I think it also all consistently points to this idea that things are getting worse for workers and much better for billionaires.”
What is causing jobless growth?
Robertson attributes weakening labor share averages to the rise in automation, which he noted is displacing workers, with productivity—a metric essentially measuring worker output—continuing to rise. Second-quarter GDP data showed nonfarm productivity growth grew 1.4% last quarter, though the rate has slowed from 2.2% in the same quarter a year ago.
“All these things, bit by bit, are replacing people, and they’re concentrating income and their share of capital,” he said.
Goldman Sachs analysts Joseph Briggs and Sarah Dong estimated in a report, based on Department of Labor job numbers, that AI automation could displace 25% of all work hours. They predicted that over the course of the AI adoption period, a 15% increase in AI-driven productivity would displace 6% to 7% of jobs, and, at its peak, a 1 million increase in unemployed workers, though job displacement as a result of AI has not shown up meaningfully in any economic data.
The displacement could be substantial, the analysts said, but said the impacts of automation will be tempered by a wealth of new jobs created as a result of the technological changes.
Automation is expected to be a boon to corporate profits and GDP, projected to boost GDP by 1.5% by 2035, according to a Wharton brief published in September 2025. Early signs indicate AI could drive productivity gains, with around 80% of employees reporting AI makes them faster at specific tasks, but only 37% of companies seeing an impact of that productivity on operating profits, according to McKinsey data, and AI operating costs continue to constrain its deployment.
Robertson added that growing unemployment, which he expects to see rise over the next few months, keeps wages down, allowing margins and profits to expand.
To be sure, the recent productivity surge has been an “open question,” Morgan Stanley economists have argued, not unanimously attributed to increased adoption of AI or automation. The analysts suggested this increase would be cyclical, or vestiges of pandemic-era habits of companies making more from less.
An Oxford Economists research brief from earlier this year suggested companies are disguising overhiring-related layoffs as a result of AI, but said automation-related workforce reductions have not yet happened en masse. Additionally, while unemployment has been ticking up over the past year, it is still relatively low.
Why is an immigration crackdown backfiring on U.S. labor?
Mark Regets, senior fellow at National Foundation for American Policy (NFAP), sees a different reason for a slowing workforce. He told Fortune President Donald Trump’s immigration crackdown has not done what Trump administration officials, such as White House Deputy Chief of Staff Stephen Miller, said it would in increasing the number of U.S.-born workers. Instead, according to Regets, Trump’s immigration policies have not only decimated the foreign-born workforce, but has also created fewer opportunities for domestic-born workers to find jobs.
NFAP data shows a 1.1 million to 1.4 million-person reduction in the foreign-born workforce since January 2025, consistent with the
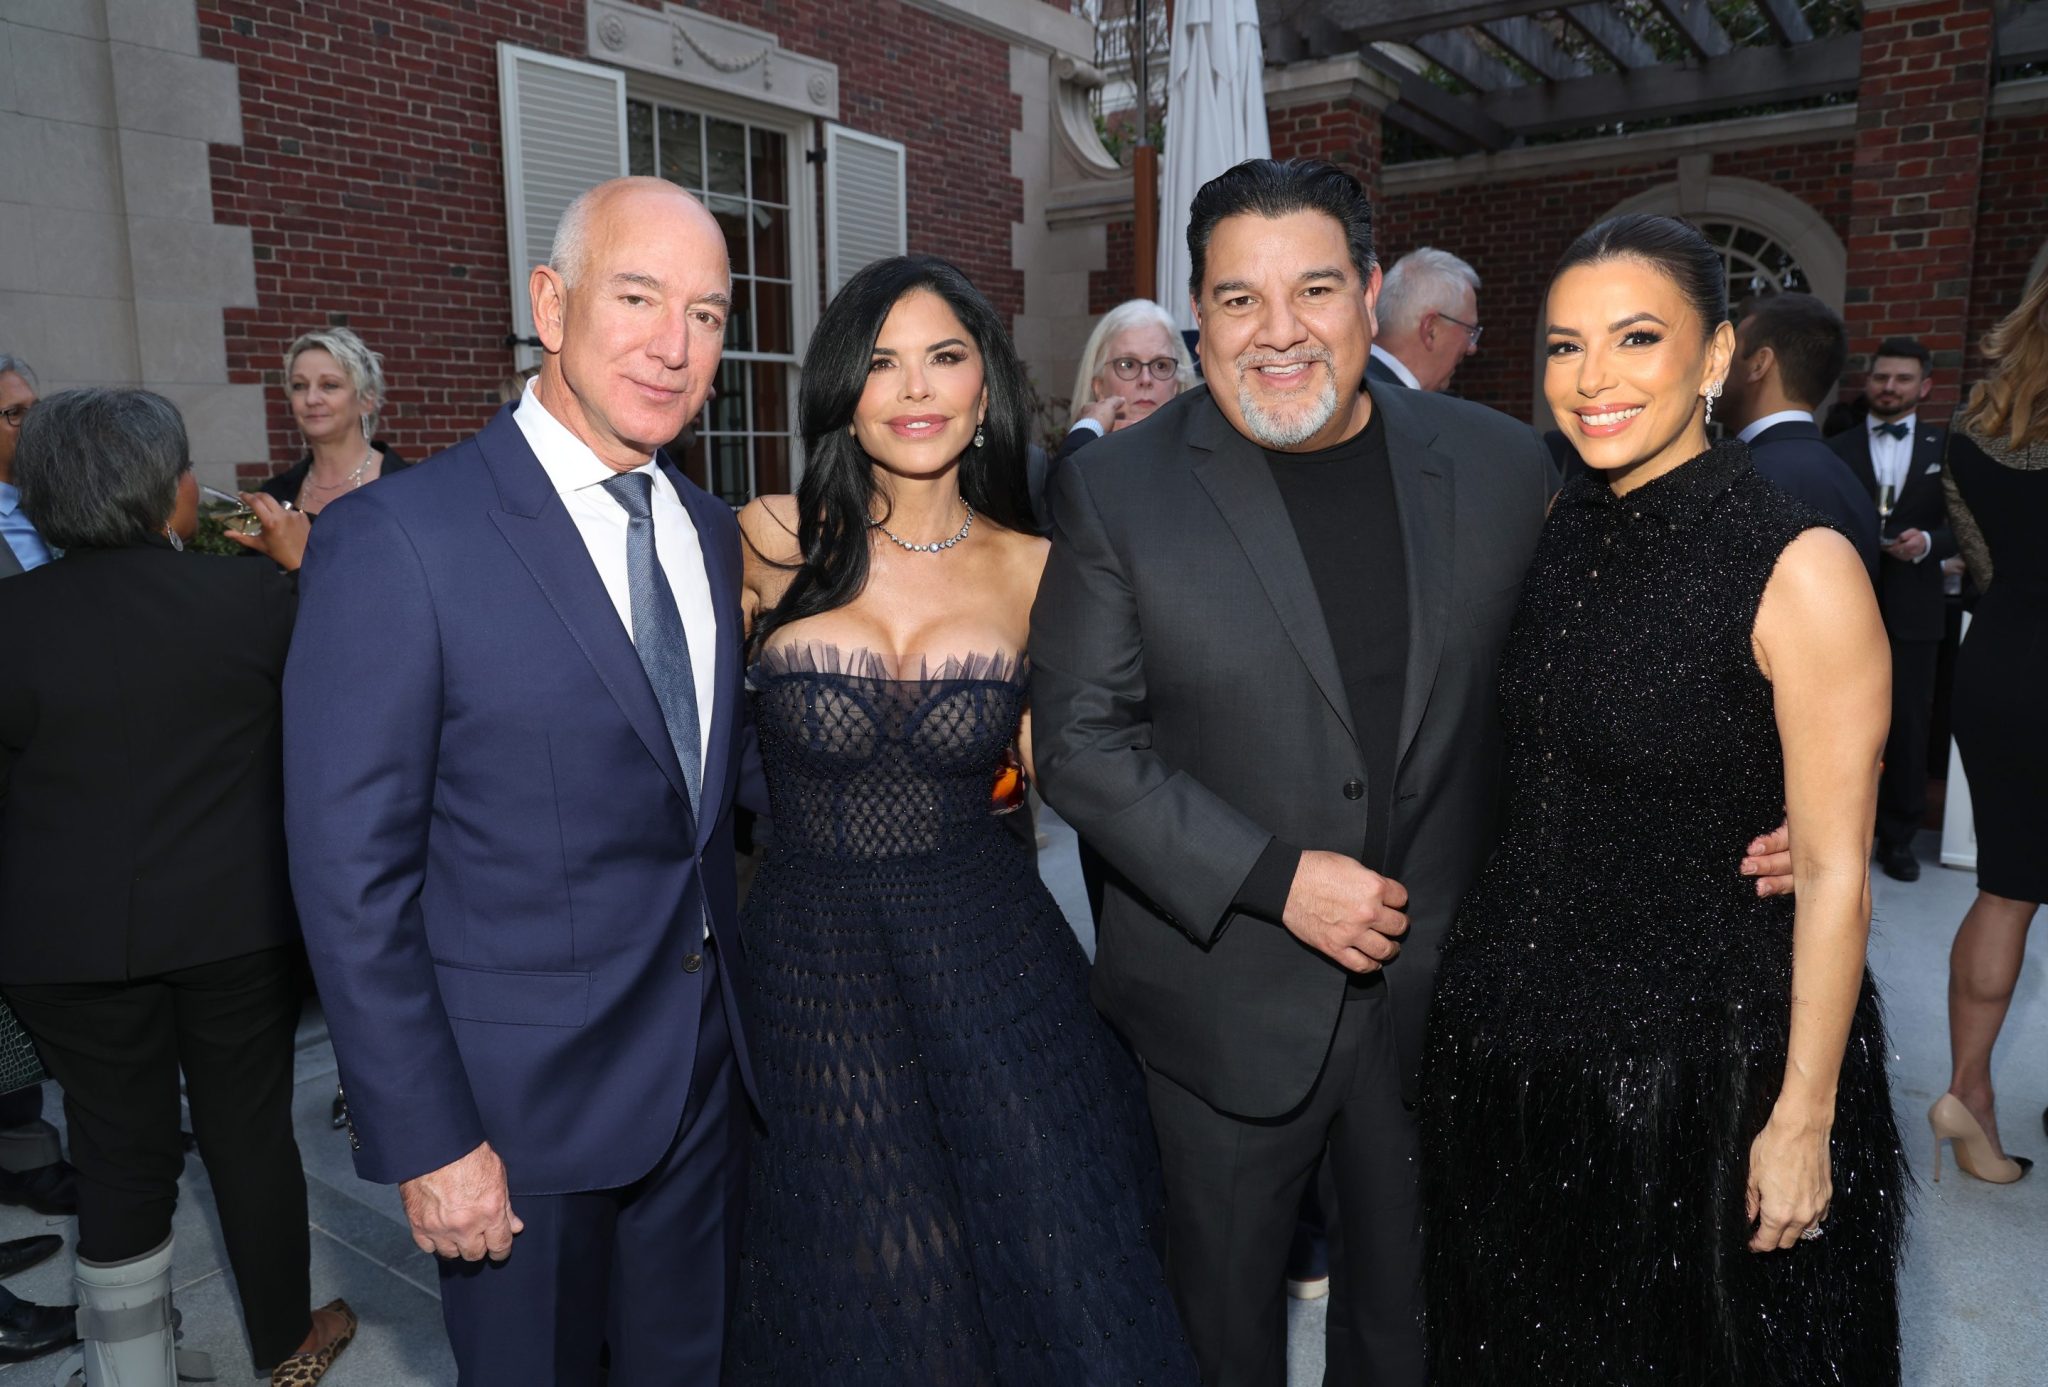
Jeff Bezos once gave Eva Longoria and the admiral behind Osama bin Laden’s capture $100 million—but she says you don’t need wealth to give back
A lot of people talk about changing the world. But Amazon’s billionaire founder, Jeff Bezos, gave Eva Longoria $50 million to actually do it. And two years on, she says the biggest myth still surrounding philanthropy is that you have to be rich to do it.
“One of the biggest misconceptions about philanthropy is that impact is tied to wealth or scale, when in reality, impact comes in many forms,” the Desperate Housewives star told Fortune. “What I’ve learned is that impact doesn’t come from how much money you have, it comes from how you show up.”
It’s a message that feels pointed at a moment when billionaire philanthropy dominates headlines and ordinary people assume giving back is someone else’s job.
For Longoria, the most powerful—and most overlooked—form of change happens at street level. “Mentoring someone, supporting small business, sharing what you know—those things matter because not everyone has access to capital or resources, but anyone can be part of someone else’s support system,” she adds. “And I think that’s really what’s missing for a lot of people. They don’t have someone in their corner.”
What Eva Longoria did with Jeff Bezos’s $50 million
The actress is practicing what she preaches. Having built a net worth north of $80 million thanks to a sprawling business portfolio—including a luxury tequila brand Casa Del Sol, the media company Hyphenate Media Group, a stake in women’s soccer team Angel City FC, and an early investment in the multibillion-dollar John Wick franchise. Now she’s channeling paying it forward by mentoring small-business owners through a new partnership with Lenovo.
She’s also been running the Eva Longoria Foundation since 2012 to improve educational and entrepreneurial opportunities for Latinas in the U.S., as well as Eva’s Heroes, a charity that helps young adults with “intellectual special needs,” according to its website.
Bezos and his wife, Lauren Sánchez Bezos, launched the Courage and Civility Award in 2021 for individuals who make significant contributions to society. They’ve given millions (often $100 million) to help those in need. Previous recipients include CNN host and civil rights advocate Van Jones, chef and humanitarian José Andrés, and late country legend Dolly Parton—who famously helped fund Moderna’s COVID-19 vaccine research.
It’s why Longoria says receiving the prize, alongside Bill McRaven, a retired Navy admiral, is much bigger than the money.
“Receiving that support was incredibly meaningful, not just because of the scale of the gift, but because it represented trust and responsibility,” Longoria said, adding that she’s been “more intentional and more strategic” in how she shows up as an advocate.
“This award has allowed me to continue investing those resources into the communities and causes I care deeply about—supporting Latina entrepreneurs, expanding access to education, and backing organizations that are driving real change on the ground,” she added. “The Courage and Civility Award makes it possible for us at the Eva Longoria Foundation to create long-term impact with transformative giving.”
McRaven, who oversaw the 2011 raid that killed al Qaeda leader Osama bin Laden, pledged to use his share of the money to develop education programs for future military leaders and the children of deceased veterans, as well as mental health support for those who serve.
You don’t have to be a billionaire to make a difference
Longoria isn’t the only one making the case that you don’t need to be rich and famous to make a difference.
Just look at the Giving Pledge—the commitment, cofounded by Bill Gates, Melinda French Gates, and Warren Buffett, that asks the ultrawealthy to donate at least 50% of their fortunes—has attracted more than 250 signatories since its launch in 2010.
The number who have actually followed through? A handful—fewer than 10. Most fulfilled the pledge only after their deaths.
It’s why Liz Baker, CEO of Greater Good Charities, says we “can’t afford” to wait on billionaires to solve the world’s problems.:“I think if everybody did something to help in their community, we wouldn’t have the issues that we have.”
The global nonprofit she runs has distributed more than $1 billion in impact across 121 countries since 2006—and she also told Fortune the idea that giving back has to be some grand, expensive gesture is one of the biggest things holding people back.
“Everybody can chip in—and it doesn’t even have to be money. Like, do something,” she said.
“Even if you’re like, I have one hour a week to solve this problem in my community that I care about,” Baker said. “Figure out how to do that. Most local nonprofits need help.”
A version of this story originally published on Fortune.com on April 21, 2026.
Read more exclusive interviews from Fortune’s Orianna Rosa Royle:
Mark Zuckerberg’s $170 million Miami mansion is just one piece of his sprawling real estate empire that includes a 196-year-old castle
With a net worth of $222 billion, Mark Zuckerberg is one of the richest people in the world and the owner of a massive real-estate portfolio that spans the entire U.S.
His latest purchase from August is a 440-acre estate and accompanying 196-year-old castle in County Waterford, Ireland, a purchase that reportedly set him back 51.17 million euros, or about $57.1 million.
Yet, his priciest purchases dates back to earlier this year, when the Meta CEO and his wife, Dr. Priscilla Chan, reportedly purchased a luxury mansion on Indian Creek Island in Florida near the in-progress home of Amazon founder Jeff Bezos.
The 300-acre, man-made Indian Creek Island is near Miami and Miami Beach and contains a mere 41 lots with approximately 84 residents, the Wall Street Journal reported. Home prices on the island start at about $60 million, and records show the billionaire paid $170 million for his waterfront home with nine bedrooms and 11 full bathrooms, the Miami Herald reported. Miami-Dade County property records note the owner as a land trust.
Even an undeveloped property on the exclusive island can fetch big bucks: One vacant lot roughly the same size as Zuckerberg’s sold for a reported $105 million in 2025.
The property Zuckerberg reportedly purchased at 2 Indian Creek Island Road puts him in the most coveted area of the already exclusive island, said Mitchell Duchon, a Miami Beach–based real estate agent with the Corcoran Group who specializes in high-end waterfront properties. On the western side of the island, where Zuckerberg’s property is reportedly located, lots are about 80,000 square feet, compared with about 50,000 square feet on the east side, according to Duchon. On this side, where Amazon founder and fellow billionaire Jeff Bezos also owns two lots, residents have better access to the open water of Biscayne Bay and a more expansive view with great sunsets, he added.
“That side of the island is perceived to be the most appealing,” Duchon said.
Bezos has been buying up properties on Indian Creek Island since he announced in 2023 he was leaving Seattle for Florida. The Amazon founder first purchased a $68 million home that would end up being just a few doors down from Zuckerberg’s in 2023. Near the end of that year, he paid another $79 million for a neighboring property with the intention of combining the lots into a single compound—a trend Duchon said is increasingly common among wealthy buyers because of the scarcity of truly expansive waterfront properties in the area. Meanwhile, Bezos is reportedly living in a third Mediterranean-style property also on Indian Creek Island, on the east side, which he snapped up for $87 million in 2024. Last year, Bezos sold one of his Seattle homes overlooking Lake Washington for a record $63 million, the Puget Sound Business Journal reported.
Indian Creek Island operates as an independent municipality with its own government and private police who patrol by air, water, and sky. Access to the island is controlled by a single gated bridge, making safety and privacy a defining feature. Most of the island’s interior comprises an 18-hole golf course and the Indian Creek Country Club, with a limited number of members owing, in part, to a difficult admissions process and a $500,000 initiation fee.
Zuckerberg is one of the latest billionaires to pick up a Florida property, especially in light of a proposed ballot initiative to be voted on in California next week that would impose a one-time 5% “billionaires tax” for any individual worth at least $1 billion dollars retroactive to Jan. 1, 2026. (To be sure, Zuckerberg still very much calls California home, having invested $50 million through Meta for a Sacramento downtown revitalization and AI-focused project earlier this year.) Google cofounder Larry Page also snagged a $71.9 million home in Miami’s Coconut Grove neighborhood in January that he plans to combine with another property to form a total $173 million waterfront compound.
Indian Creek Island, in particular, is home to a number of high-profile names, who, besides Bezos, include the financier Carl Icahn and former NFL quarterback Tom Brady.
Zuckerberg’s reported newest property is just the latest addition to the tech CEO’s growing portfolio of luxury homes across the U.S.
Palo Alto compound
Zuckerberg’s home base remains Palo Alto, where, according to the New York Times, he owns 11 properties in the Crescent Park neighborhood. Over more than a decade, Zuckerberg has poured $110 million into buying adjacent properties, in some cases drawing complaints from his neighbors.
Hawaiian estate
On the island of Kauai, about 100 miles northwest of Honolulu, Zuckerberg owns a $300 million property commonly known as Koʻolau Ranch, spanning roughly 1,400 acres. He quietly added about 1,000 additional acres to the compound last year, Architectural Digest reported, bringing his total Kauai holdings to more than 2,300 acres.
The ranch is one of Zuckerberg’s most secretive properties. Alm
Tech stocks just lost more than $1 trillion in a day—a gothic horror test for the ‘moats’ Warren Buffett taught Wall Street to love
Markets are ushering in a particularly gothic Halloween as the AI trade exposes a crumbling aristocratic pile of early 21st century capitalism. Wall Street has been describing itself in castle-adjacent terms for years.
Jamie Dimon has long talked to JPMorgan shareholders about the bank’s “fortress balance sheet.” His 2015 letter set aside a section to answer the question of what the phrase even meant. By 2021, he’d added a second castle word, warning that “the moats that protect this company are not particularly deep.”
The moat came from Warren Buffett. In a 1999 Fortune article with Carol Loomis, he argued that the key to investing is a company’s competitive advantage and how durable it is, and that the businesses worth owning have wide moats around them.
The gothic novel’s favorite picture of danger is a castle falling apart, and for about 250 years the two have traded images: the castle and the moat, the vampire, the creature built in a lab. This Halloween season has them rushing to the front of the conversation, with a two-day rout in tech stocks on Thursday and Friday turning on whether the AI giants’ moats will hold, as gothic horror booms on bookshelves and movie screens.
Horror took 15.5% of the domestic box office in 2025, according to The Numbers, and U.S. horror book sales rose 7% through the first nine months of 2025, per Circana BookScan, while adult fiction overall grew just 1%. The New York Times asked Friday why every book is gothic now, with publishers putting the label on everything from family sagas to space operas, and several film critics commenting that Nathan Fielder’s smash-hit business-scandal documentaryYou Can See Everything is a twisted, even gothic romance in the tradition of Alfred Hitchcock.
The moats get tested
The selling started with Alphabet. The stock fell 12.6% Thursday, wiping out roughly half a trillion dollars in market value, after the Google parent’s quarterly report. Revenue from the core search unit fell short, partly because of the popularity of less-profitable “AI mode” searches and the company burning cash faster than expected. Its free cash flow came in at negative $9.1 billion, against the negative $2.23 billion analysts expected, per FactSet.
The S&P 500’s worst performer was software giant ServiceNow, which dropped 27% the same day on slowing revenue growth and disappointing guidance. By Friday morning, it was Amazon’s and Intel’s turn, with Intel down roughly 25% before the opening bell. Big Tech lost nearly $900 billion in market value after another sharp rise in AI spending in the third quarter, the Financial Times calculated. Nasdaq 100 companies lost more than $1 trillion in market value Friday alone. Reddit, whose shares fell more than 22% premarket Friday, is pulling up the drawbridge: it’s moving to a logged-in experience as AI eats search.
The irony is spooking investors. AI is eating into the businesses that throw off the cash, and the cash is going into AI anyway. The hyperscalers have raised $326 billion in stock and bonds this year to pay for the build-out, more than triple 2025, according to S&P Global Market Intelligence data.
The question underneath it is the one Apollo chief economist Torsten Slok put to clients the morning Alphabet fell. “With AI disruption potentially around the corner, there is a lot of discussion about moats at the moment,” he wrote in his Daily Spark note Thursday.
He built on finance professor Aswath Damodaran, the “dean of valuation,” who compiled a list of sources of competitive advantage, including brand strength, switching costs, network effects, cost advantages and legal protection. Then he boiled it down to an AI moat checklist of three questions: does the company own data its rivals can’t get, is its product part of how customers do their jobs every day, and can it charge more without customers walking away?
Judging by that third test, the companies selling AI don’t seem to measure up. OpenAI’s new GPT-6.1 Terra model costs up to half as much per token as the version before it. An index from expense-management firm Ramp, which looked at what companies actually pay Anthropic and OpenAI, shows token prices down roughly 35% since the end of June, in what Axios called a price war.
The companies paying for AI aren’t getting much back yet, either. In an Oct. 24 note, Slok sent a tremor through Wall Street terminals with an argument that AI “has delivered zero financial payoff to corporate America outside of tech.” Revenue per worker and profit margins are rising for the Magnificent Seven and flat for the rest of the S&P 500, he noted, and mainstream companies are starting to treat token spending as a cost center that weighs on margins rather than a source of growth.
The first castle was a fake
Xavier Aldana Reyes, a researcher at the Manchester Centre for Gothic Studies, told the Times that interest in the gothic tends to surge during periods of social anxiety and political turmoil. Literary agent Mary C. Moore put the genre’s subject more bluntly, telling the paper that “Gothics are all about exposing what is rotten at the core of something shiny/wealthy.”
The genre was invented by a scion of wealth who knew the old order from inside and drew a salary without working at all. Horace Walpole was the son of UK Prime Minister Robert Walpole, and hisThe Castle of Otranto, published in 1764, is generally regarded as the first gothic novel.
He passed it off as a translation of an obscure Italian work, found in the library of an old Catholic family in northern Eng
AI boom hits a wall on Wall Street as OpenAI cuts fundraising target while Meta gets a credit warning over its cash flow, spending and monetization
The seemingly endless gusher of capital that’s been showered on Silicon Valley during the AI boom may be coming to an end soon as Wall Street pushes back on massive spending plans.
Following a brutal selloff in tech stocks over the past week, OpenAI slashed the target on its latest fundraising round to $20 billion from $30 billion, sources told the Financial Times. That also cut its expected valuation to $1.25 trillion from $1.4 trillion.
The funding round was also upstaged by Anthropic, according to the report, as OpenAI’s arch-rival prepares to go public next month. Ahead of its IPO, Anthropic filed an S-1 on Monday that showed revenue has soared and its cash flow turned positive in the first half of this year.
OpenAI didn’t immediately respond to a request for comment.
The timing couldn’t have been worse. Quarterly earnings reports from hyperscalers this week spooked investors. Alphabet saw its cash flow sink deeper into negative territory in the third quarter, with the Google parent also joining Meta and Amazon in charging ahead with massive spending plans. On Thursday, Alphabet fell about 12%, its worst day on record.
To be sure, there were other positive signs as well, in addition to Anthropic’s bullish S-1. Microsoft reported strong cloud growth and stayed cash flow positive, though it said its capital spending will accelerate, while AI chip maker SK Hynix blew away earnings forecasts.
But the narrative had already turned bearish, especially after AI debt fears sent shares and bonds of “neocloud” companies tumbling earlier this month.
At the same time, OpenAI was seeking more capital just as other AI giants tapped financial markets heavily. This past week alone, Elon Musk said SpaceX closed $40 billion in debt financing, Meta announced plans to raise $95 billion in equity, and Microsoft raised $25 billion in a bond sale.
The prospect of hyperscalers continuing to hemorrhage funds was too much for S&P Global, which cut its outlook on Meta to “negative” from “stable” late Friday, citing negative cash flow and uncertainty around capital expenditure plans.
The credit ratings agency maintained Meta at AA- but warned the social media leader’s leverage could top 1.0x as soon as 2027, which is the downgrade threshold for the current rating. That’s up from about 0.1x in 2025 and primarily reflects its strategy of leasing data center capacity rather than from its debt issuance.
Meanwhile, S&P sees Meta’s capex reaching $140 billion this year, topping $225 billion in 2027, hitting $252 billion in 2028, and then flattening out from there. As a result, it expects free operating cash flow to remain negative: -$22 billion this year, -$71 billion in 2027, and -$39 billion in 2028.
Of course, other hyperscalers are spending heavily and running cash deficits, but S&P also said Meta’s ability to monetize its AI investments is more limited than that of its peers.
“While we believe the company intends to monetize these investments via improved advertising tools that support faster ad revenue growth, as well as from the development of new revenue streams stemming from its introduction of agentic apps such as Muse, it is unclear when these revenue streams will generate material contributions that exceed their rising costs over the next few years,” S&P said.
Meta’s rivals, however, are monetizing their data centers by leasing compute capacity, including to frontier model labs and enterprise customers, it added.
In a statement to Fortune, a Meta spokesperson said the company disagrees with S&P’s assessment of its AI monetization capabilities, pointing to “significant product and business opportunities” ahead.
“Meta is already delivering stronger engagement, better recommendations, and greater returns for businesses as a result of AI investments,” the spokesperson continued. “We believe the technology and infrastructure we’re building now will open new revenue streams, create long-term shareholder value, and bring us closer to delivering personal superintelligence to everyone.”
The bearish environment on Wall Street also comes as rising bond yields have sent borrowing costs sharply higher, the political backlash against data centers is expected to help Democrats retake Congress, and the Iran war could re-escalate after midterm elections.
Still, some bullish voices aren’t convinced the AI boom is about to go bust, and even think some retrenchment is a good thing.
According to market veteran Ed Yardeni, the AI investment boom faces financial, physical, and political constraints. If any of these constraints worsen, stocks could dive further, especially considering that AI is now a major driver of corporate earnings and GDP growth, he said in a note this week.
“However, we view these constraints as healthy for the durability of the AI boom!” he added.
For example, if the supply of capital doesn’t flow as easily, it could lead to more efficient allocation, lowering the risk of overinvestment. Yardeni expects hyperscalers to retain access to financing—thanks to their strong balance sheets—and keep spending.
In his view, it all comes down to the U.S. economy, which he said has performed remarkably well over the past few decades. Even the midterm elections are unlikely to derail it, regardless of which party controls Congress.
“Further AI jitters therefore could set up buying opportunities rather than signal the end of the boom,” he said.
This story was originally featured on Fortune.com
China sees the yuan vs. dollar rivalry like Pepsi vs. Coke, expert says — ‘never the market leader, but serviceable in a pinch’
Heavy is the head that wears the crown, and contrary to popular belief, Beijing doesn’t want the yuan to dethrone the dollar as the world’s dominant currency, according to a top China scholar.
While China has been trying to internationalize the yuan, also known as the renminbi, it doesn’t want the obligations that come with being the global reserve currency, Zongyuan Zoe Liu, senior fellow for China studies at the Council on Foreign Relation, wrote in Foreign Affairs this month.
To truly take the dollar’s place would require open capital markets, which would threaten the Communist Party’s control over who gets capital and how, she explained. That’s as many elites rely on offshore dollar holdings as a type of insurance against domestic political persecution.
Since China actually prefers to keep the dollar on top, the real reason for promoting the yuan abroad is to prevent the U.S. from weaponizing the financial system against it, Liu added, similar to how Russia was shut out after it invaded Ukraine in 2022.
A yuan network that’s international enough, even without being dominant, could bypass any dollar-based sanctions the U.S. might impose in the future.
“Placing a respectable second, or even a consequential third, would suffice to break the dollar’s effective monopoly and constrain the United States’ ability to impose financial sanctions unilaterally, while saving China the effort and cost of sustaining currency supremacy,” she said.
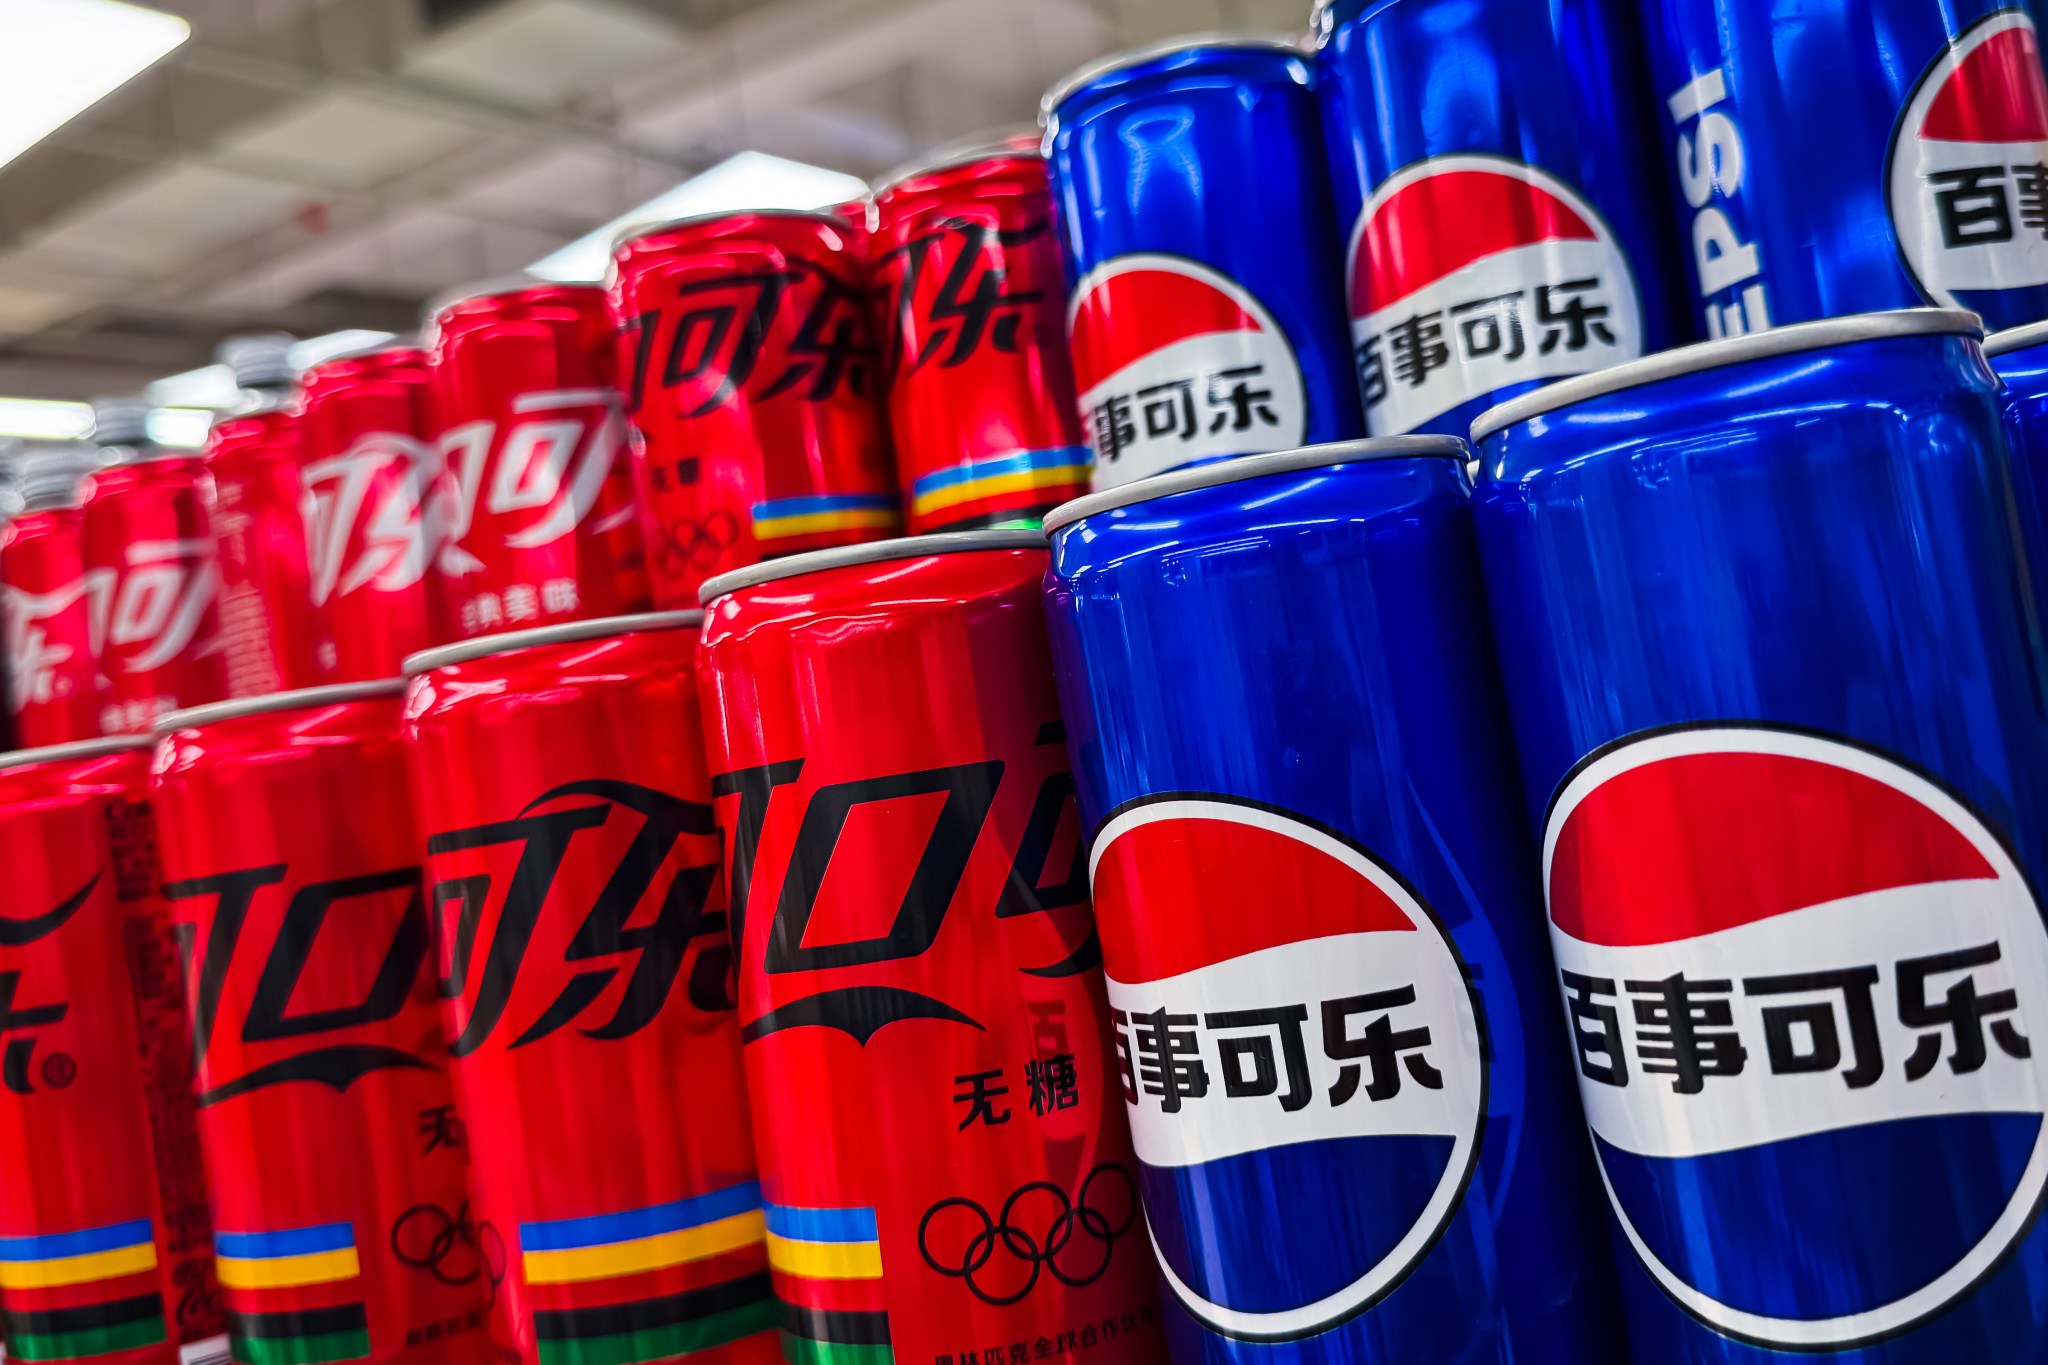
“From Beijing’s perspective, the mission is to establish the renminbi as the Pepsi to the dollar’s Coca-Cola: never the market leader, but serviceable in a pinch and more than capable of keeping the dominant incumbent honest.”
(For what it’s worth, Pepsi has actually fallen further behind Coke in the cola wars and was dealt a major symbolic defeat recently when KFC said it would replace PepsiCo soft drinks with Coca-Cola’s products at its 3,700 U.S. restaurants.)
So far, China facilitates renminbi use among firms in more than a hundred countries and across a growing array of commodity markets. As of June, its Cross-Border Interbank Payment System had 1,829 participants who could send payments to more than 5,200 banks in 191 countries.
Global currency requirements
But that’s just a small fraction of what the U.S.-dominated system processes, Liu said, adding that a global currency also entails pricing, financing, risk transfer, and reinvestment.
Chinese exporters still invoice in dollars and convert them to yuan just before brining them into China. But Beijing is promoting “China prices,” or yuan benchmarks on domestic commodity exchanges and has succeeded with lithium, she noted.
The financing stage is gaining momentum too as Chinese banks have more than doubled their yuan lending to overseas borrowers between 2023 and mid-2026. The People’s Bank of China has also reached currency swap agreements with 32 foreign central banks and monetary authorities.
More modest steps have increased the yuan’s presence in risk transfer markets as state firms have begun settling cargo insurance in yuan. But reinvestment is perhaps the weakest link in the chain. A strong yuan ecosystem requires recipients to hold and reinvest their balances rather than convert them, Liu argued.
China has expanded overseas access to domestic stocks and bonds, but Beijing’s unpredictable capital controls remain a worry. In March, foreign investors held just 1.6% of the Chinese bond market versus 27% in the U.S. bond market.
“Without a far larger pool of renminbi assets that foreigners can freely buy and sell, the renminbi cannot come close to replacing the dollar,” she said.
But similar to how the “petrodollar” anchors the greenback’s role in global trade, the yuan can dominate trade in an essential good that China controls.
That could take the form of critical minerals, clean energy equipment, and electrical infrastructure used in green energy technology, Liu posited.
China has already established supremacy across much of the green supply chain and is promoting standards built around technologies Chinese-owned firms.
“If China consolidates its dominance over that industrial ecosystem, using its scale and cost advantages to prevent competitors from catching up, it could gain enough leverage to price those essential, hard-to-substitute exports in renminbi, creating the foundation for a ‘green yuan’ that might eventually replace the petrodollar,” she predicted.
Petroyuan
Meanwhile, the Iran war has raised doubts about the petrodollar, which goes back to a deal struck in 1974 when Saudi Arabia agreed to price its oil in dollars and invest surpluses in U.S. assets.
In exchange for Saudi Arabia recycling its dollars back into the U.S., Washington guaranteed the kingdom’s security, which also involved stationing troops in the region, providing advanced weapons, and ensuring free navigation in the Strait of Hormuz.
But America’s role in the Mideast looks vastly different today. Despite 40 days of punishing bombardment of Iran and round-the-clock protection of commercial ships, the U.S. still hasn’t fully restored traffic in the strait.
At the same time, Iran’s swarms of missiles and drones have inflicted significant damage on U.S. aircraft, radars and bases, while American air-defense systems have failed to completely protect Gulf allies’ critical energy infrastructure.
“Damage to Gulf economies could encourage an unwind in their foreign asset savings,” Deutsche Bank warned in March. “In this context, reports that the passage for ships through the Strait of Hormuz may be granted in exchange for oil payments in yuan should be closely followed. The conflict could be remembered as a key catalyst for erosion in petrodollar dominance, and the beginnings of the petroyuan.”
This story was originally featured on Fortune.com
Meta outlook revised downward by S&P on cash flow and capex concerns
Generalized belief states in transformers
Many thanks to Xavier Poncini, Paul Riechers, Fernando Rosas, and Matt Smith for useful conversations.
1. Introduction
Despite the recent successes of transformers and other sequence models, there are still many open questions about their basic principles of operation. For example, what internal representations do these models use for prediction and generation? Can we decode, interpret, and manipulate such representations? Is it even possible to consider a notion of representation without reference to an external world model?
To make progress on these questions, I propose a general way to define, decode and manipulate representations in sequence models. The approach is centered on the concept of "generalized belief states", statistics of past observations that satisfy a few criteria: (1) they are sufficient for predicting future data, (2) they can be recursively updated as new observations come in, and (3) they are low-dimensional, allowing for visualization and interpretation. I show that such generalized belief states can be mapped to the internal activations and dynamics of a sequence model, allowing for decoding and manipulation of the model's representations. I illustrate the ideas using a tractable toy model, a transformer trained on a simple HMM stochastic process, where we will see that the KV cache plays a key role.
This post is directly inspired by the 2024 paper "Transformers Represent Belief State Geometry in their Residual Stream" by Adam Shai, Paul Riechers, and collaborators. That paper introduced the idea of studying belief states in transformers, and proposed a method for doing so using tractable toy models. I recommend reading that paper if you haven't already, though it is not a prerequisite for understanding my post. Section 5 compares this approach with the one developed in that paper.
2. Belief states
We start at a general level, by considering the problem of sequence prediction. Imagine that we observe a history of previous tokens and then wish to predict the next token . We assume that sequences are drawn from a stochastic process . For now, it does not matter whether this process comes from real-world data or a generative model.
Before proceeding, we introduce a bit of notation. indicates the token alphabet, indicates the set of finite-length sequences (including the empty history ), and indicates the set of probability distributions over the alphabet . We write for the set of histories with positive probability under the stochastic process.
2.1 Hidden Markov models
To optimally predict the next token after observing history , we must compute the conditional distribution . We may now ask: what information should we track in order to compute this distribution? How should this information be updated as new tokens arrive? Does this information represent some unobserved latent aspect of the stochastic process?
These questions have a straightforward answer when the stochastic process is described as the output of a hidden Markov model (HMM). Given an HMM description, we can write the probability of any history as [1] where is the hidden state of the HMM at step , is the probability of emitting token and transitioning to hidden state from hidden state , and is the initial distribution over hidden states. Using this expression and Bayes' rule, the next-token distribution can be written in a factorized form as Here, is the Bayesian posterior distribution over the hidden state, conditioned on the observed history . This posterior distribution corresponds to the beliefs of a Bayesian observer about the underlying states of the generating process, and in the literature, it is called a belief state. [2]
Belief states satisfy two important properties: sufficiency and recurrence. Sufficiency means that the belief state allows us to predict the next token just as well as if we knew the whole history , as seen from the prediction map in Eq. (1a). Recurrence means that, after observing a new token , the updated belief state can be computed from and alone. In particular, using Bayes' rule, we can write the update map as
In addition to sufficiency and recurrence, belief states have several other attractive properties. For instance, the prediction map (1a) is time-independent and linear in . Time-independence lets us interpret belief states at different steps in the same way; linearity lets us interpret predictions as convex mixtures of those made by individual hidden states. The update map (1b) is also time-independent and "nearly" linear, being a ratio of two linear functions of the belief state. (In fact, without loss of generality, we may instead consider "unnormalized" belief states , which update in a purely linear way . [3] )
In practice, belief states are often encoded as nonnegative vectors: where is the number of hidden states of the HMM. In this way, each belief state is a nonnegative -dimensional vector that sums to 1, so it belongs to a -dimensional affine subspace of . For HMMs with few hidden states, belief states belong to a low-dimensional space, allowing for easy visualization and interpretation. Also, in this space, belief states often exhibit a remarkable fractal structure, which arises from the recursive nature of the update map. [4]
2.2 Example
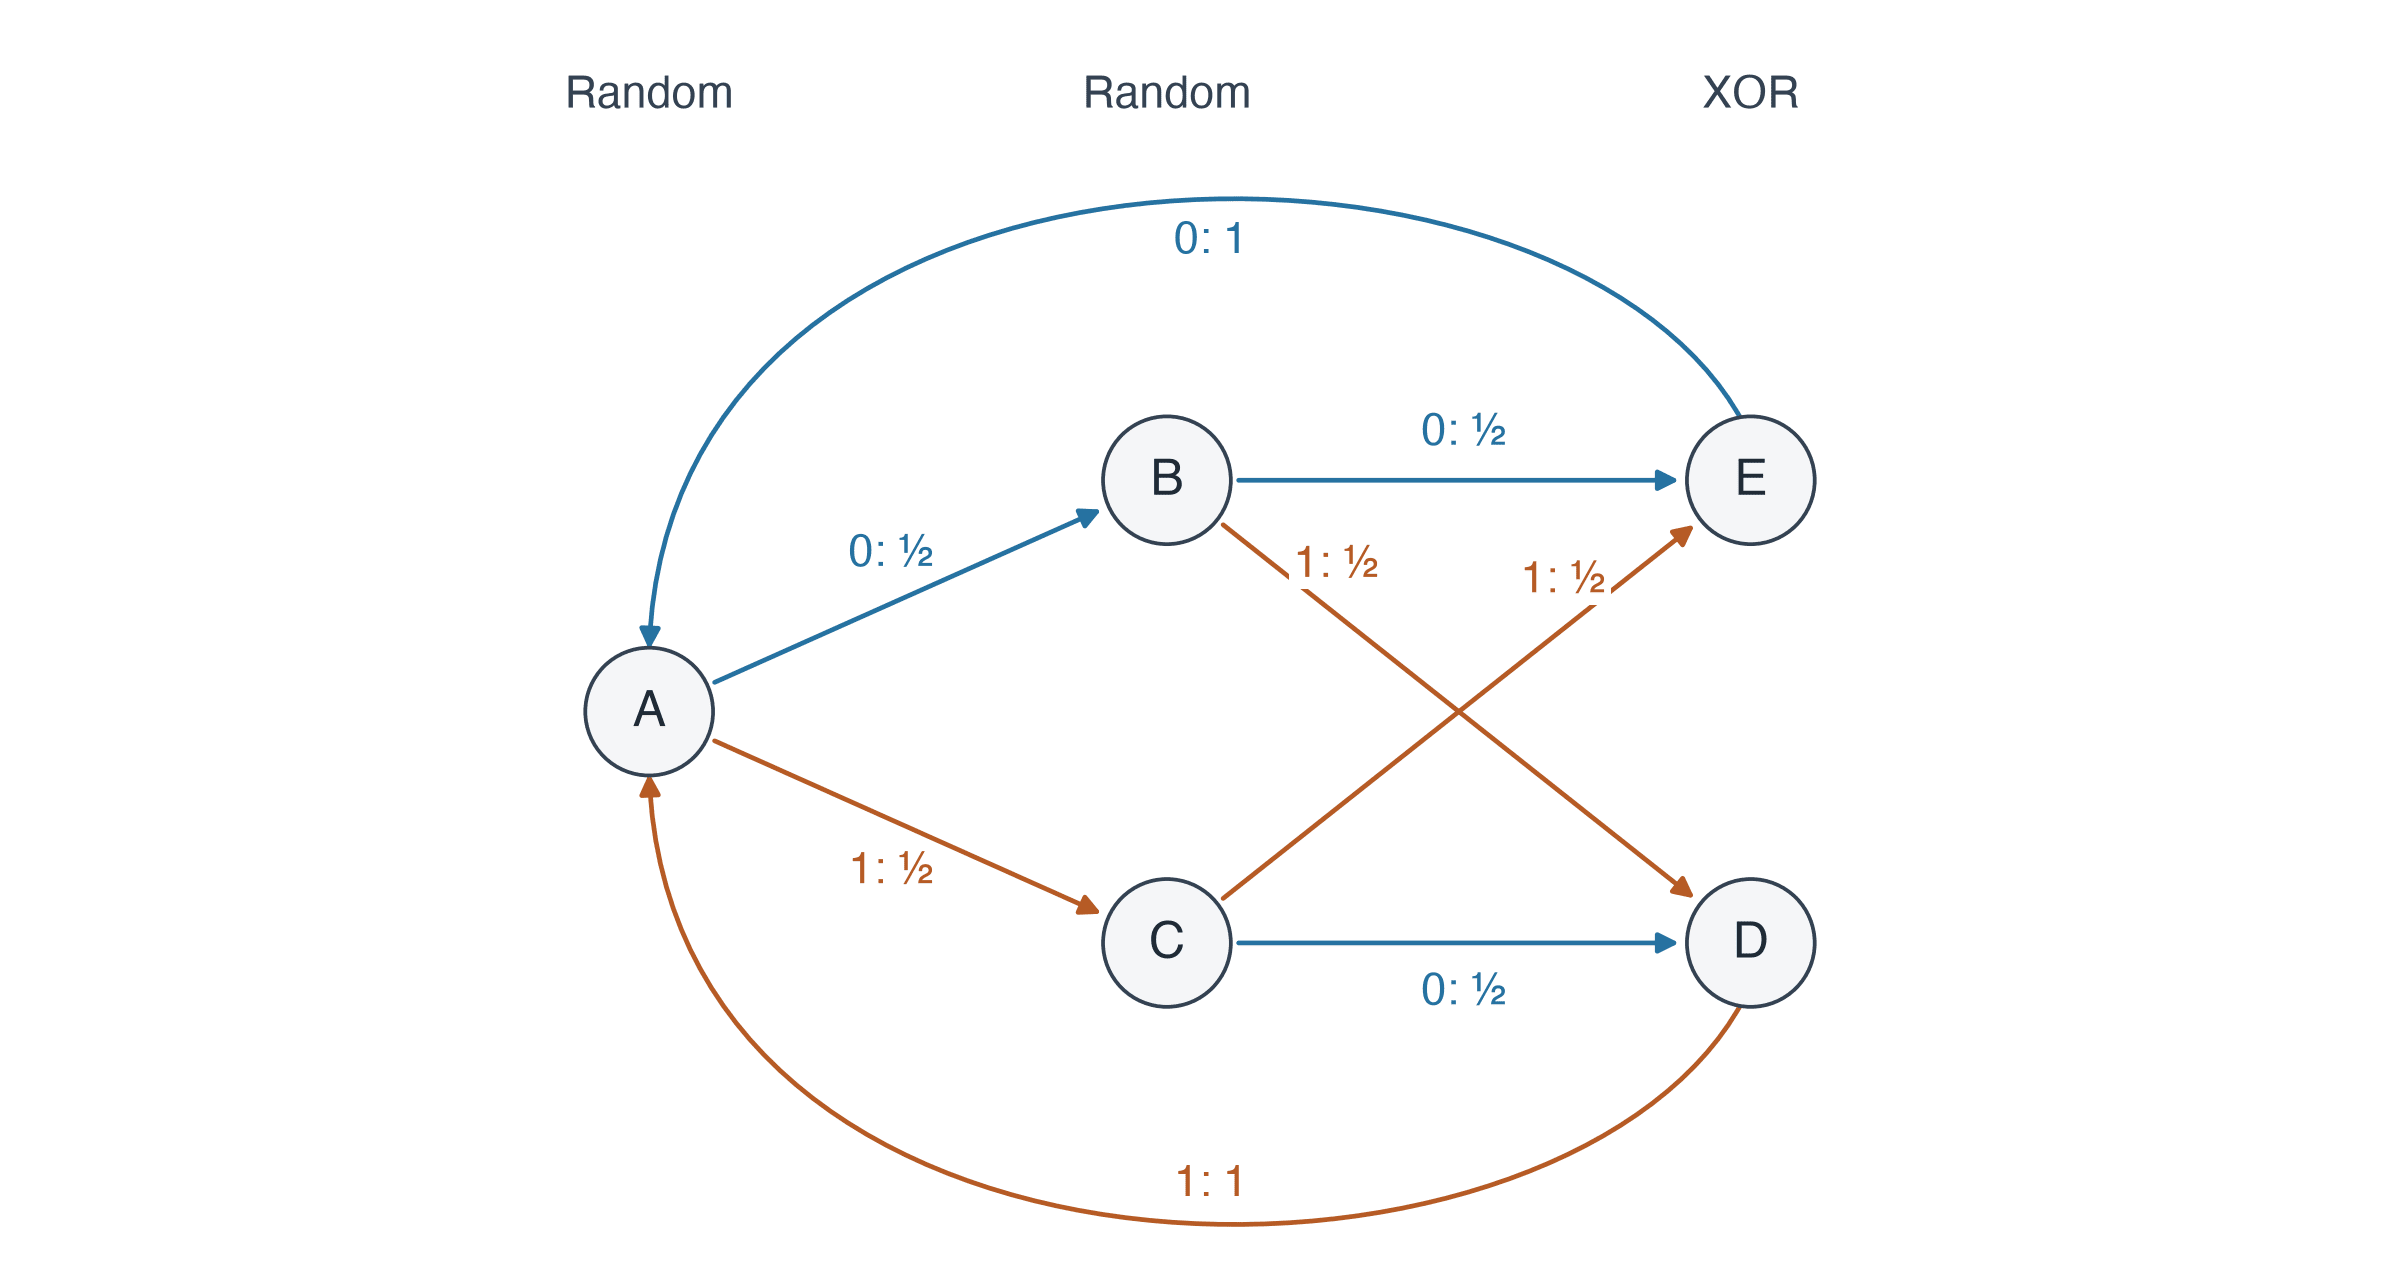
To make things concrete, we now introduce a running example: a stochastic process called MRRXOR that is generated by an HMM with five hidden states. [5] The HMM emits two independent random bits, then their XOR, and then resets. In addition, at each time point, the hidden state can jump to another random hidden state with probability ; if this random jump occurs, it does not emit a token and is immediately followed by an ordinary transition. The HMM is shown in the following figure, with each transition labeled by its emitted bit and probability. (For visual clarity, the random jumps between hidden states are not shown.)
Next, we illustrate the geometry of belief states for this HMM. We compute the belief states after each of the possible histories of length . Each belief state is a normalized nonnegative vector that belongs to a four-dimensional affine hyperplane of .
We visualize these vectors using principal component analysis (PCA), showing all six pairs of the four non-trivial principal components. Each belief state is colored by the last two tokens of the history, with its point area proportional to the history probability. Black dots correspond to each of the five hidden states A–E.
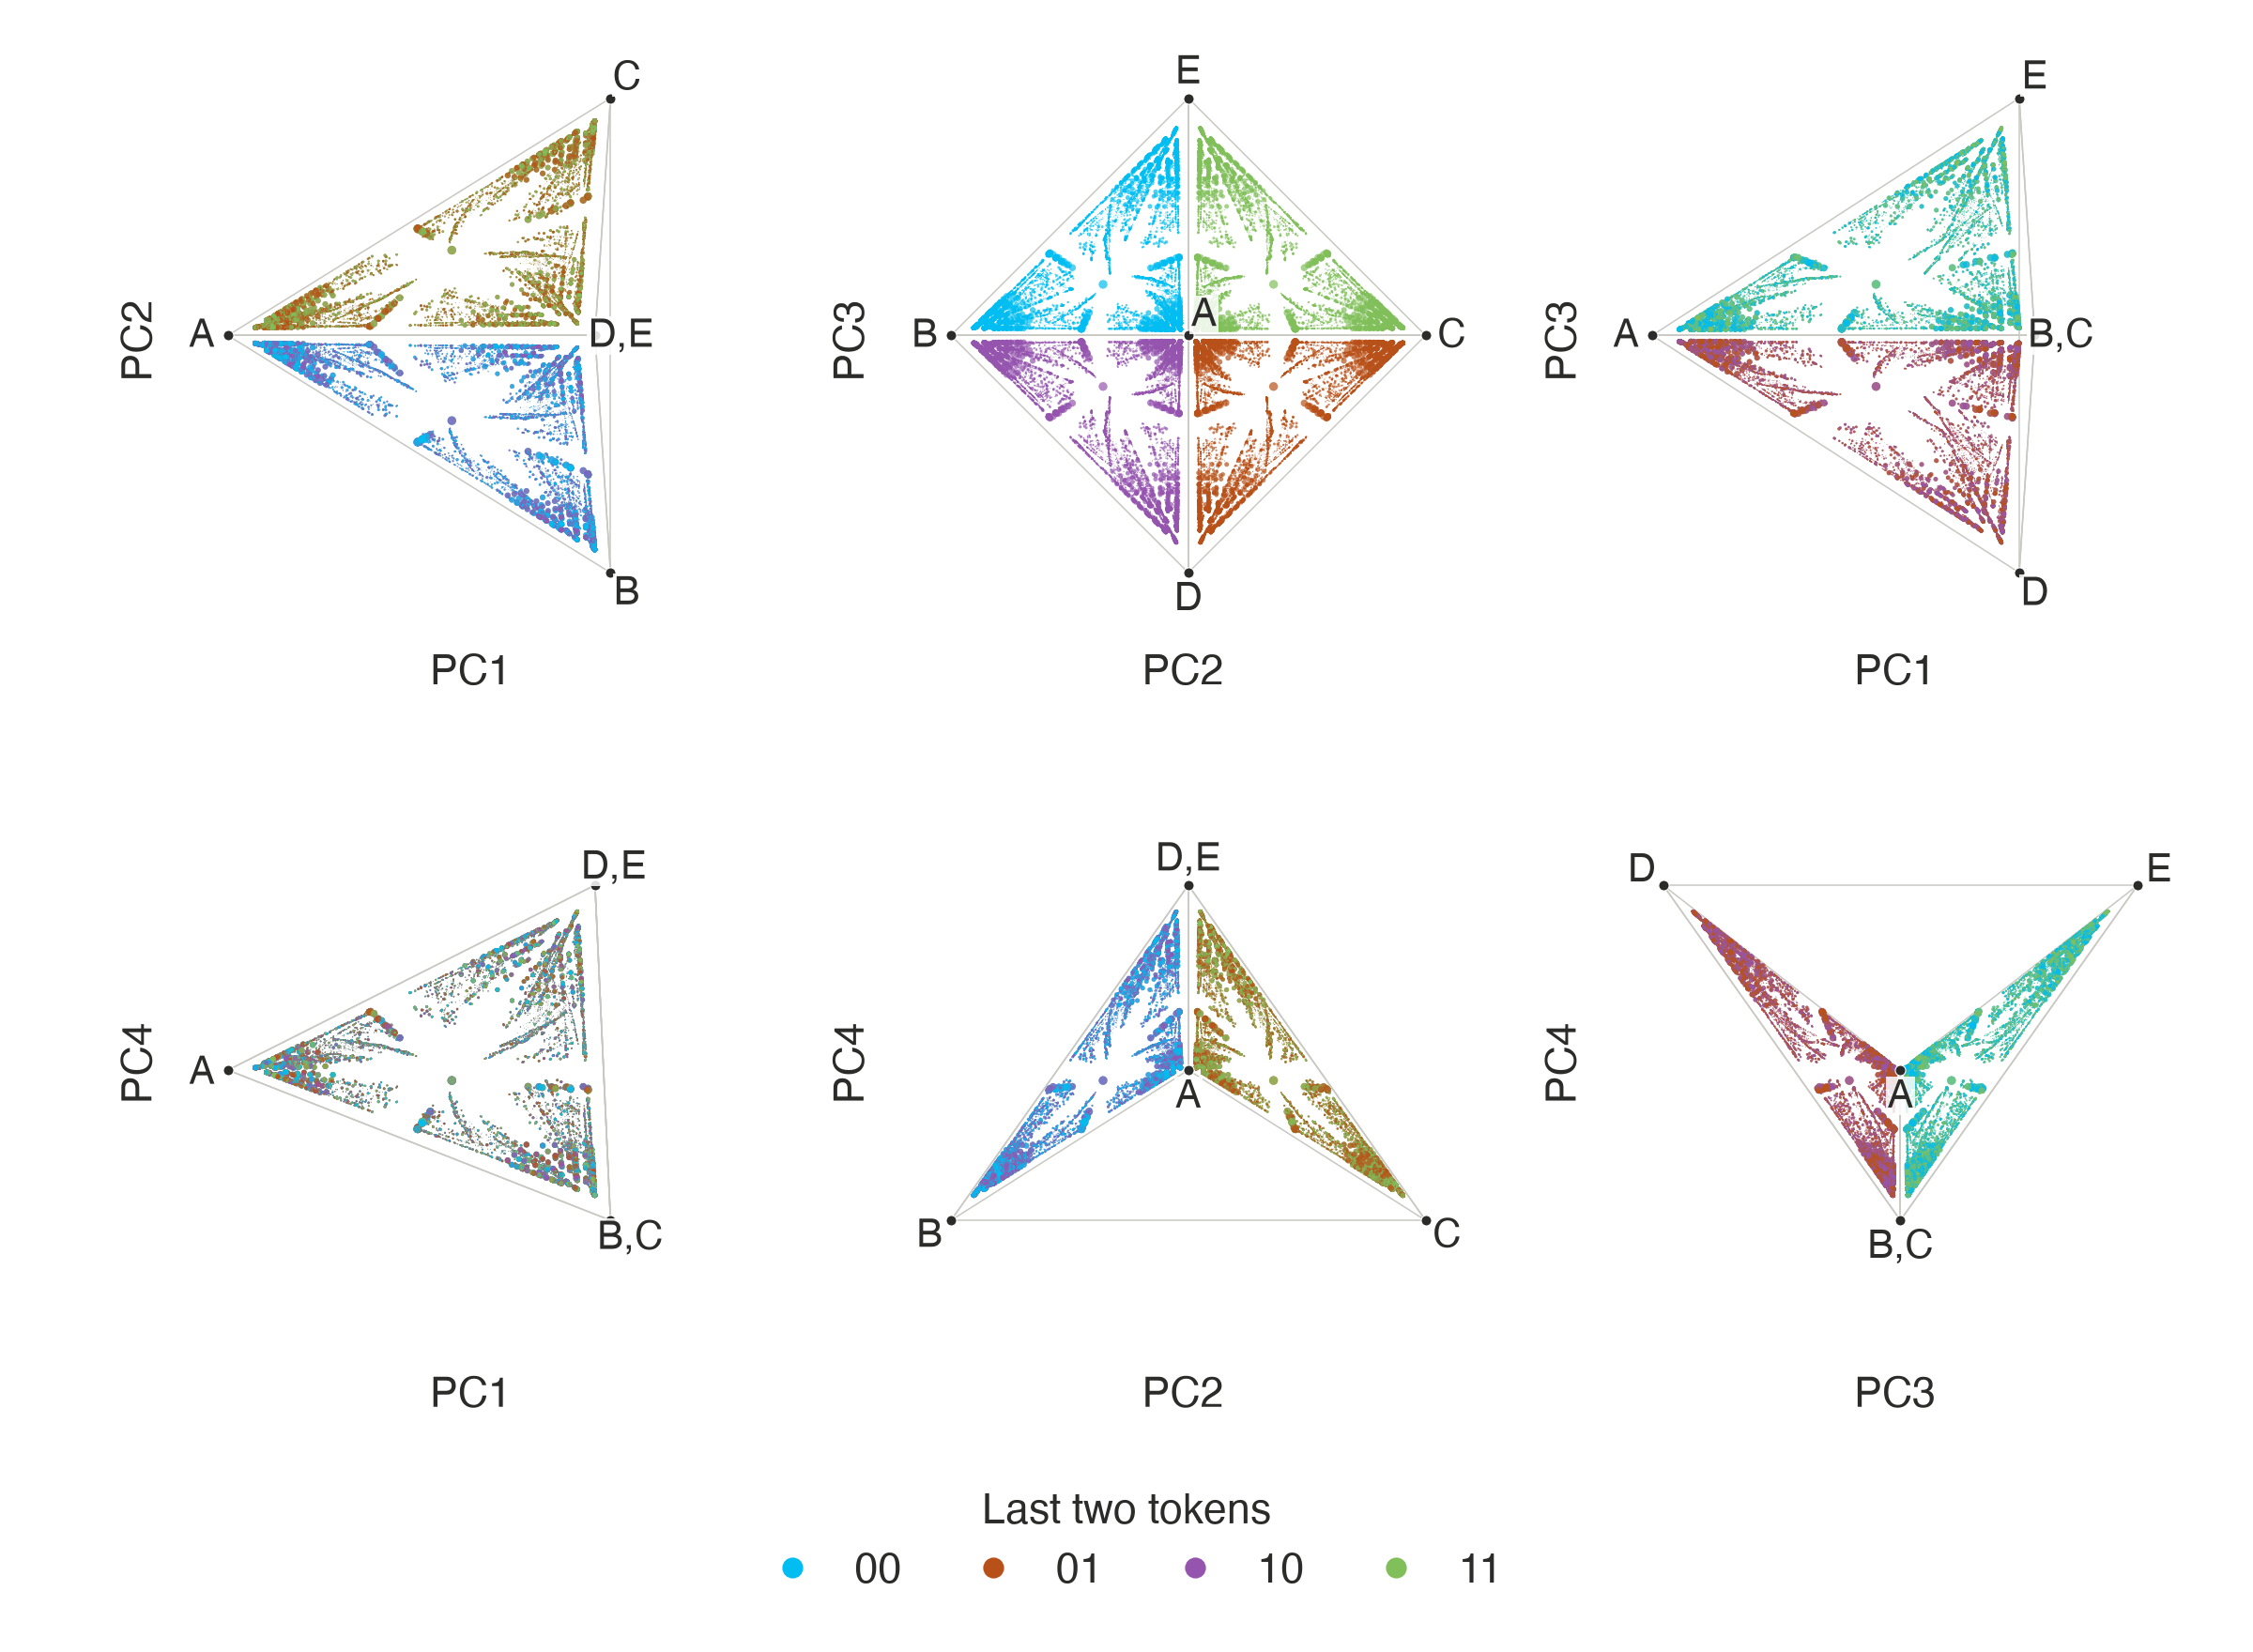
PC1 largely tracks the probability of the "reset" state A, i.e., the belief that an XOR triple has just been completed. PC2 separates histories by their last token. PC3 s